Skip to content
Myhomeetal
Menumyhomeetal
ShopAll productsCategoriesDealsNew arrivalsBest sellersBrandsβ˜… My Club
AccountSign inCreate account
Import fromUnited StatesUnited KingdomChinaJapanBrazil
ExploreDownload appOwn a homeBlog & NewsroomHelp & SupportReturnsPrivacy
Trending searches
iPhone
Samsung phones
Smart TVs
Laptops
Power banks
Washing machines
Myhomeetal
Trending searches
iPhone
Samsung phones
Smart TVs
Laptops
Power banks
Washing machines
Own a homeBlogHelpDownload appOrdersSign InCart
STAY CONNECTEDOffers, new arrivals and useful updates
Myhomeetal
ShopCategoriesBrandsAll productsDeals & offersβ˜… My Club
HelpHelp CenterTrack an orderShipping & deliveryReturns & refundsAsk myhomeetalCall +234 906 000 2626
myhomeetalAbout usNewsroom & guidesOwn a homeMy accountSaved productsRefer & earn
Import fromUnited StatesUnited KingdomChinaJapanBrazilGlobal sourcing
Mobile app

Shop, track orders, manage your wallet and account from your phone.

Download our appAndroid & iPhone
JOIN US
Β© Copyright 2026 - myhomeetal | All Rights ReservedPrivacy PolicyTerms of UseCookie SettingsReturns & RefundsShipping & Delivery
HomeShopSavedCartSign in
MyHomeEtal Home Ownership Guide

Owning a home starts with understanding your options.

Explore legitimate home-financing programmes in Nigeria, learn what you may need to qualify, and apply through the official channels β€” without confusing financial jargon.

Explore mortgage optionsHow to apply
  • Official programme links
  • Private calculator
  • Plain-language steps

Independent educational guide. MyHomeEtal is not currently an authorised mortgage lender or agent of either programme.

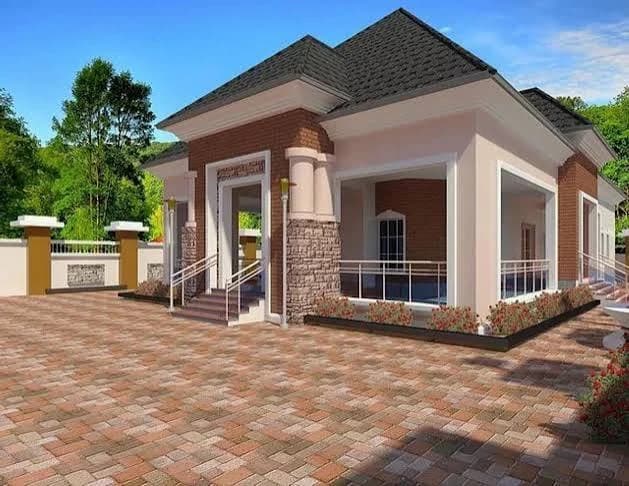
A modern Nigerian family bungalow with a brick-and-stone entrance, covered veranda and paved driveway
Example on a ₦30m home₦3,000,00010% starting deposit
BasicsProgrammesCalculatorEligibilityDocumentsStepsFAQ
The basics

What is a mortgage?

A mortgage is a loan you use to buy a home. You usually pay part of the price upfront (your deposit or equity), while a lender finances an agreed part. You then repay the loan over time, with interest. The property is usually used as security for the loan.

For example, on a ₦30 million home
10% starting deposit₦3,000,000Remaining purchase price₦27,000,000

Illustration only. The ₦27 million balance is not a promised loan amount. Your lender may require extra equity, fees, insurance and legal costs.

Verified public programmes

Two ways to explore home financing

We link directly to official programme sites, so you stay in control of your application.

Federal-government-supported

MREIF mortgage

A federal-government-supported mortgage financing initiative helping eligible Nigerians purchase homes through participating lenders.

9.75%
annual fixed rate, standard published offering
Up to 20 yrs
repayment period
10%
minimum equity contribution
  • 9.75% annual fixed interest rate on the standard published offering
  • Repayment of up to 20 years
  • Minimum 10% equity contribution
  • Subject to lender credit, income and property checks

A 10% contribution means you provide at least ₦3 million toward a ₦30 million property, before any additional closing costs. The balance is not automatically approved.

Check eligibility on MREIF β†—
First-time buyer focus

Family Homes Funds β€” Home Ownership Fund

A homeownership financing programme designed to help eligible first-time buyers, particularly low- and middle-income Nigerians, purchase homes with partner institutions.

10%
minimum deposit, subject to your funding window
Several
homeownership financing windows
Individual
rate and tenure per offering
  • Minimum 10% deposit, subject to your funding window
  • Several homeownership financing windows
  • For eligible salaried and self-employed applicants
  • Rate, tenure and approval depend on the actual offering and lender

FHFL does not publish one universal rate or repayment period for all applicants. Ask the participating institution for an individual offer in writing.

See official Family Homes Funds guidance β†—

Programme conditions can change. Always read the current official terms and request a written offer from the lender before paying any money.

Plan your budget

Estimate your monthly mortgage payment

Explore repayment amounts privately on your device. Nothing you enter is saved or sent to MyHomeEtal.

₦30,000,000
₦5m₦300m
Starting deposit (minimum 10%)
Repayment period
₦
Estimated monthly mortgage repayment₦256,100for 20 years at 9.75% fixed (illustrative)
Loan principal (illustrative)
₦27,000,000
Estimated interest over 20 years
₦34,463,892
Upfront deposit
₦3,000,000
Share of the monthly income enteredabout 51%

This is only a comparison, not an eligibility assessment. A lender will assess income, debt, credit and the property.

Illustrative MREIF repayment at its published 9.75% annual fixed rate. Calculated on a monthly reducing balance; your lender's schedule, insurance, fees, qualification and loan amount may differ. Explore privately on your device β€” nothing you enter is saved or sent to MyHomeEtal.

Check eligibility with MREIF β†—
Before applying

Could you qualify?

These are common considerations, not an approval checklist.

Nigerian applicant

The programmes target eligible Nigerians. Nationality, residency and age rules differ by funding window.

Steady, provable income

Whether employed or self-employed, you need to show you can comfortably make repayments.

Enough money to start

Prepare for at least the advertised deposit, as well as any verified legal, valuation, insurance and related costs.

Acceptable credit and property

The lender checks your existing obligations, repayment history and whether the home meets its requirements.

Documents

What should you prepare?

Tick what you already have β€” for your own planning only0 of 6 ready

The full list comes from the official programme or lender. Do not email sensitive documents to MyHomeEtal for mortgage processing.

Step by step

How to apply safely

  1. Learn the programme rules.Compare MREIF and FHFL and choose the offering that matches your situation.
  2. Check eligibility.Use the official MREIF pre-qualifier or speak with FHFL/the participating mortgage institution.
  3. Choose an acceptable property.Confirm which homes and developers the programme/lender can finance.
  4. Submit your documents to the authorised provider.The lender verifies income, identity, affordability, property and credit history.
  5. Review the written offer.Understand monthly repayments, total interest, fees, insurance and what happens if you miss payments.
  6. Complete approved payment and purchase steps.Only make required payments using payment details confirmed by the authorised provider.
Start with MREIF β†—Explore FHFL β†—
Good to know

Frequently asked questions

Is this free government housing?

No. These are home-financing programmes, not a free house giveaway. If approved, you pay your required deposit and repay a mortgage under the lender’s terms.

Does 10% mean I am automatically approved?

No. The 10% is a minimum starting equity/deposit for certain offerings. Your income, existing debts, credit assessment, property and other charges still matter.

Can I apply if I work for myself?

It may be possible. Expect to provide reliable evidence of your earnings and business activity. The lender decides what it accepts.

Can I use my pension funds?

Some eligible applicants may be able to use part of their Retirement Savings Account for equity under applicable pension rules. Confirm eligibility with your pension fund administrator and lender.

Do I pay MyHomeEtal to get approved?

No. MyHomeEtal does not approve mortgages or collect mortgage application payments through this page. Always verify charges with the authorised lender or programme.

Can MyHomeEtal guarantee a mortgage?

No. Only the relevant lending or programme institution can confirm eligibility, financing terms and approval.

After the keys

Make your new house feel like home.

When you are ready to move in, explore appliances, electronics and everyday essentials on MyHomeEtal.

Shop home essentials
Important: MyHomeEtal provides an independent information guide only. We are not the Federal Government, MREIF, Family Homes Funds, a mortgage lender, or an approved agent for either programme. We do not underwrite, issue or guarantee mortgages. External links open official sites. Information reviewed 21 November 2026. For programme support, visit MREIF contact or FHFL contact.